French property finance for UK and international buyers
French mortgages for UK and international buyers
Yes, you can borrow in France while living abroad. We prequalify you, then introduce you to the leading, reputable specialist mortgage brokers and lenders we work with.
Our guides and calculators are free to use.
Can you get a French mortgage if you live outside France?
Yes. Most lenders that accept non-residents look for a deposit of around 30%, loans usually start at about €200,000, and all your repayments, insurance included, must stay within 35% of your income. Lenders also want the loan repaid by about age 70. Allow roughly 7% to 8% on top for purchase costs on an older property.
Lenders finance a second home, a main home when you move, a buy to let or a holiday let, and commercial property on different terms. We prequalify you first, so neither you nor your estate agent wastes time, then introduce you to one of the specialists we work with, who packages your case for lenders. Read the full guide for non-residents.
Four numbers that shape a French purchase
These come from French rules rather than lender marketing, so they apply whichever bank you end up with.
35%
The most that all your loan repayments, borrower insurance included, can take from your income.
Source: HCSF, rule in force since 2022
25 years
The longest standard term, or 27 years with a deferral for new build or major works.
Source: HCSF
7-8%
Typical notaire fees and purchase tax on an older property, paid from your own funds on top of the deposit.
Source: Notaires de France, July 2025
10 days
Your cooling-off period after signing the compromis. A separate 10-day wait applies before you can accept a loan offer.
Source: Service-public.fr
Start with the numbers
Most people come to us after falling for a property, not a spreadsheet. These three calculators give you a realistic budget in a few minutes, using current French figures that carry their date and source.
Where are you buying?
Purchase tax, property types and what lenders look for all vary across France. Choose a region to start an enquiry with it filled in.
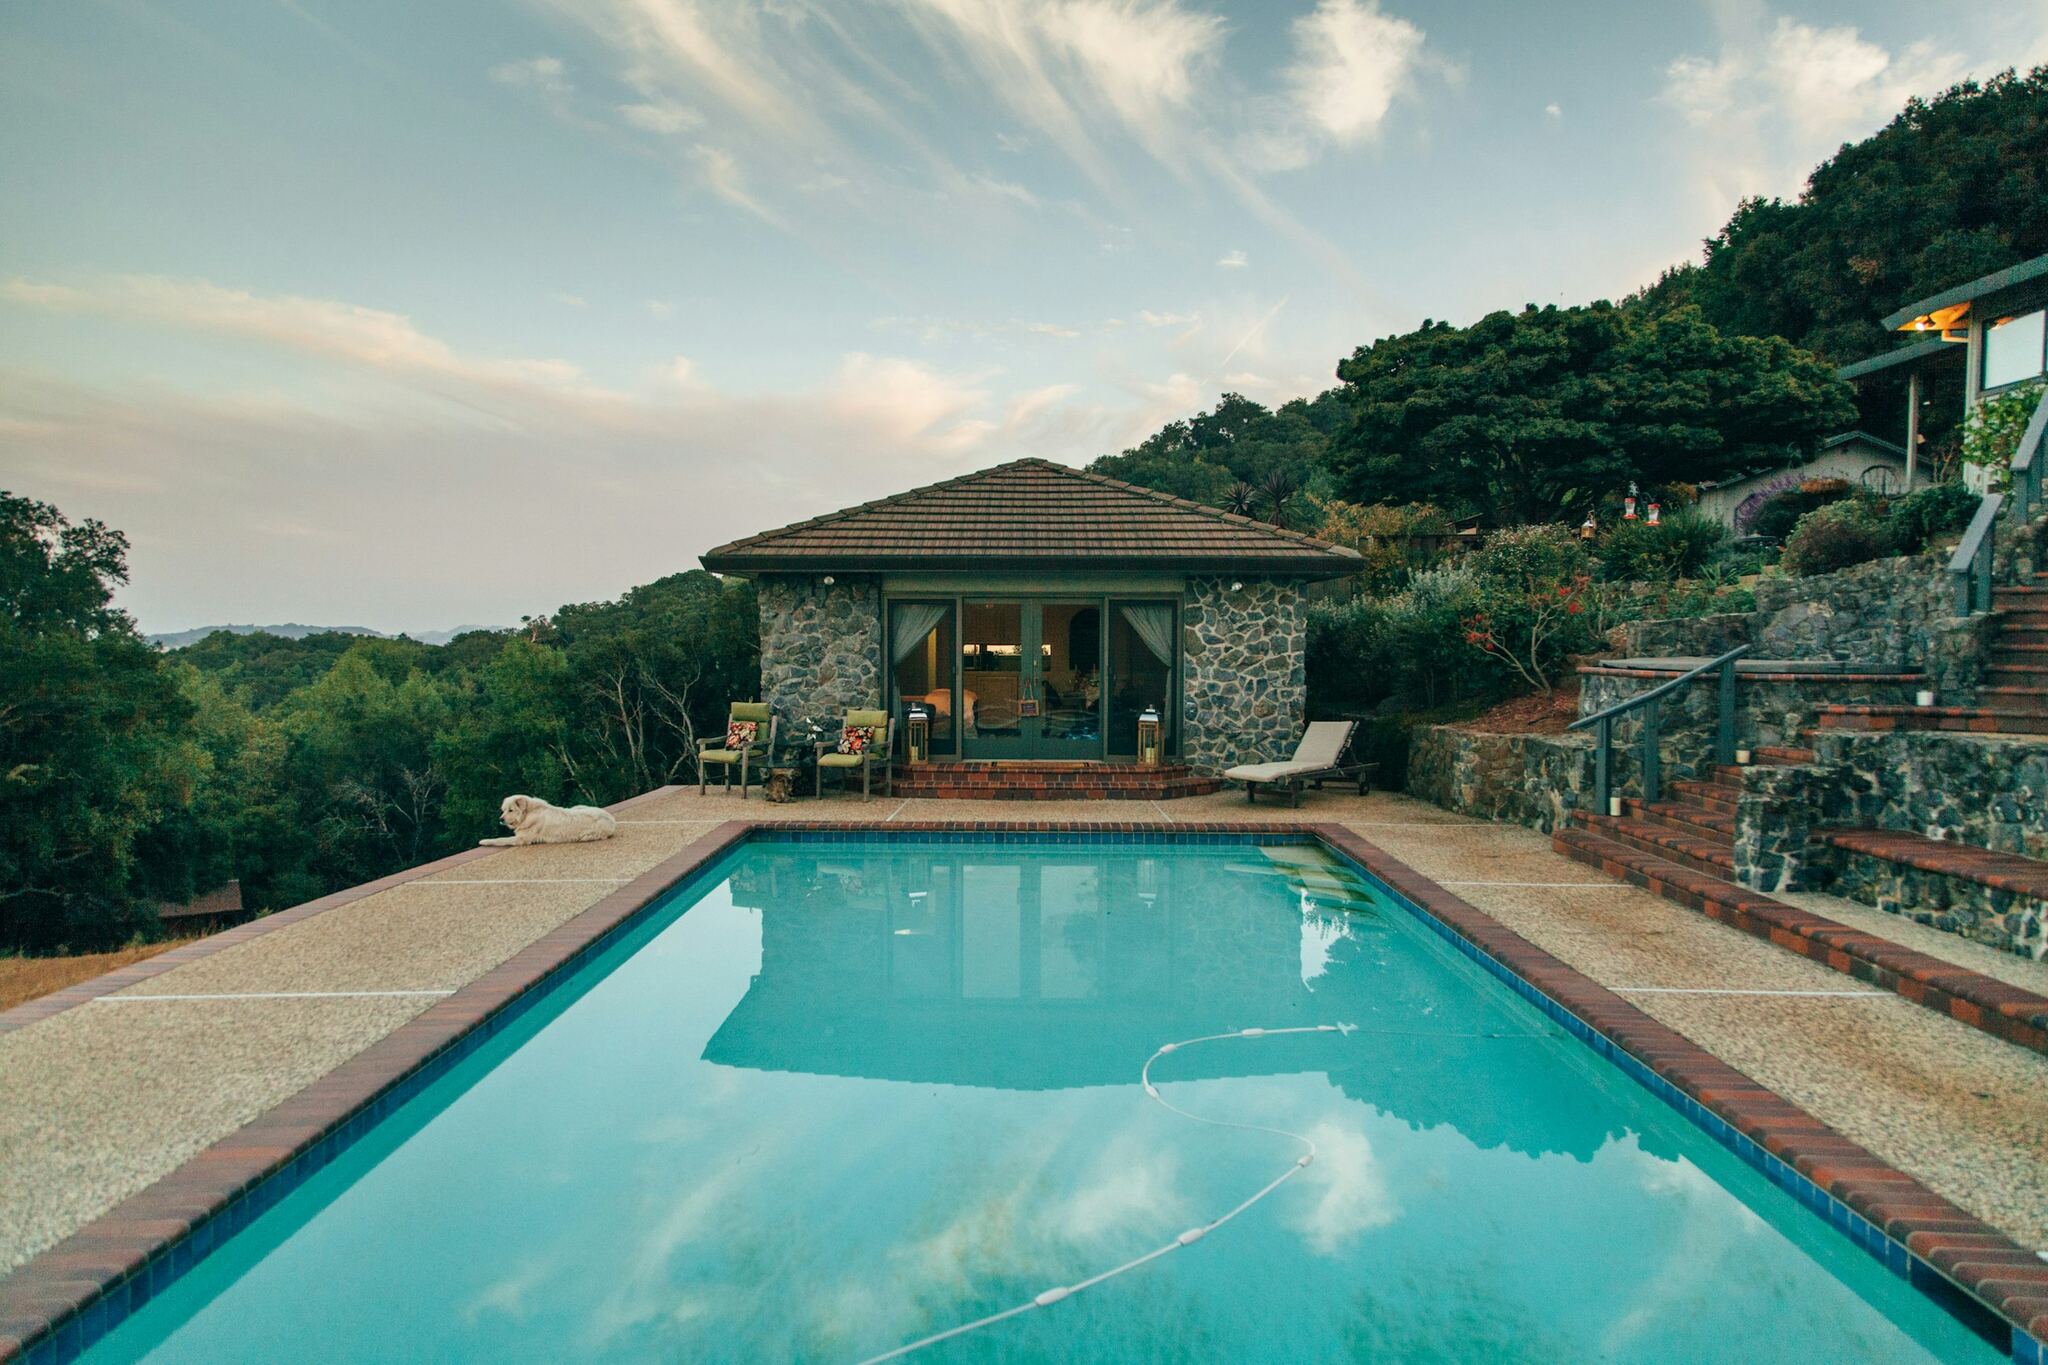 ProvenceStone mas, village houses and pools. If you plan to let the property, many lenders leave the future rent out of the affordability sums.
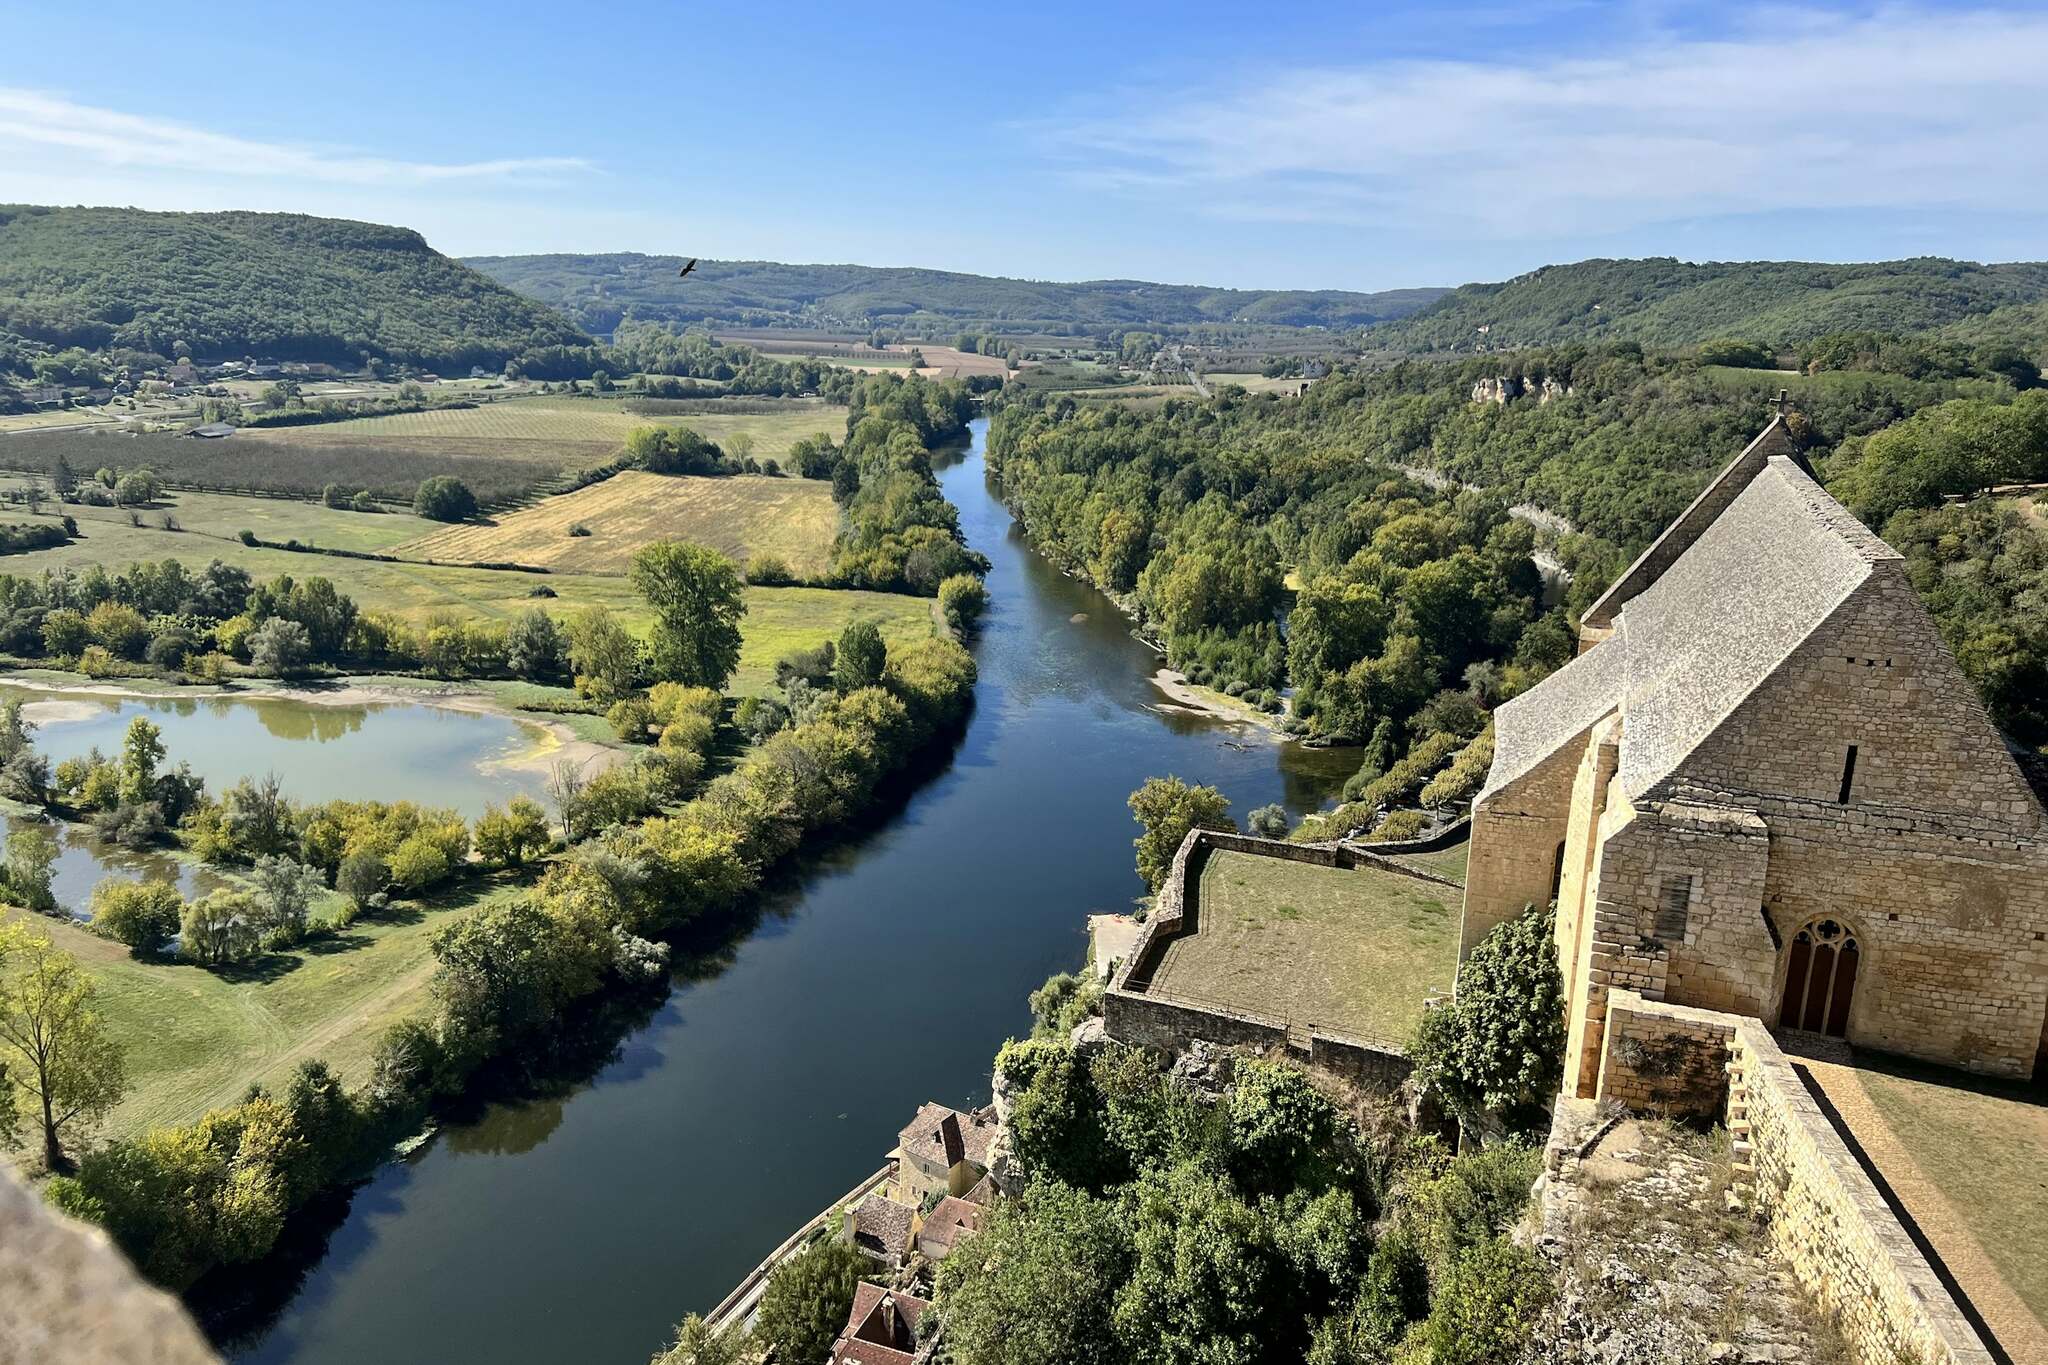 Dordogne and the LotBoth charge the 5% departmental rate, so purchase tax is about 6.32% of the price.
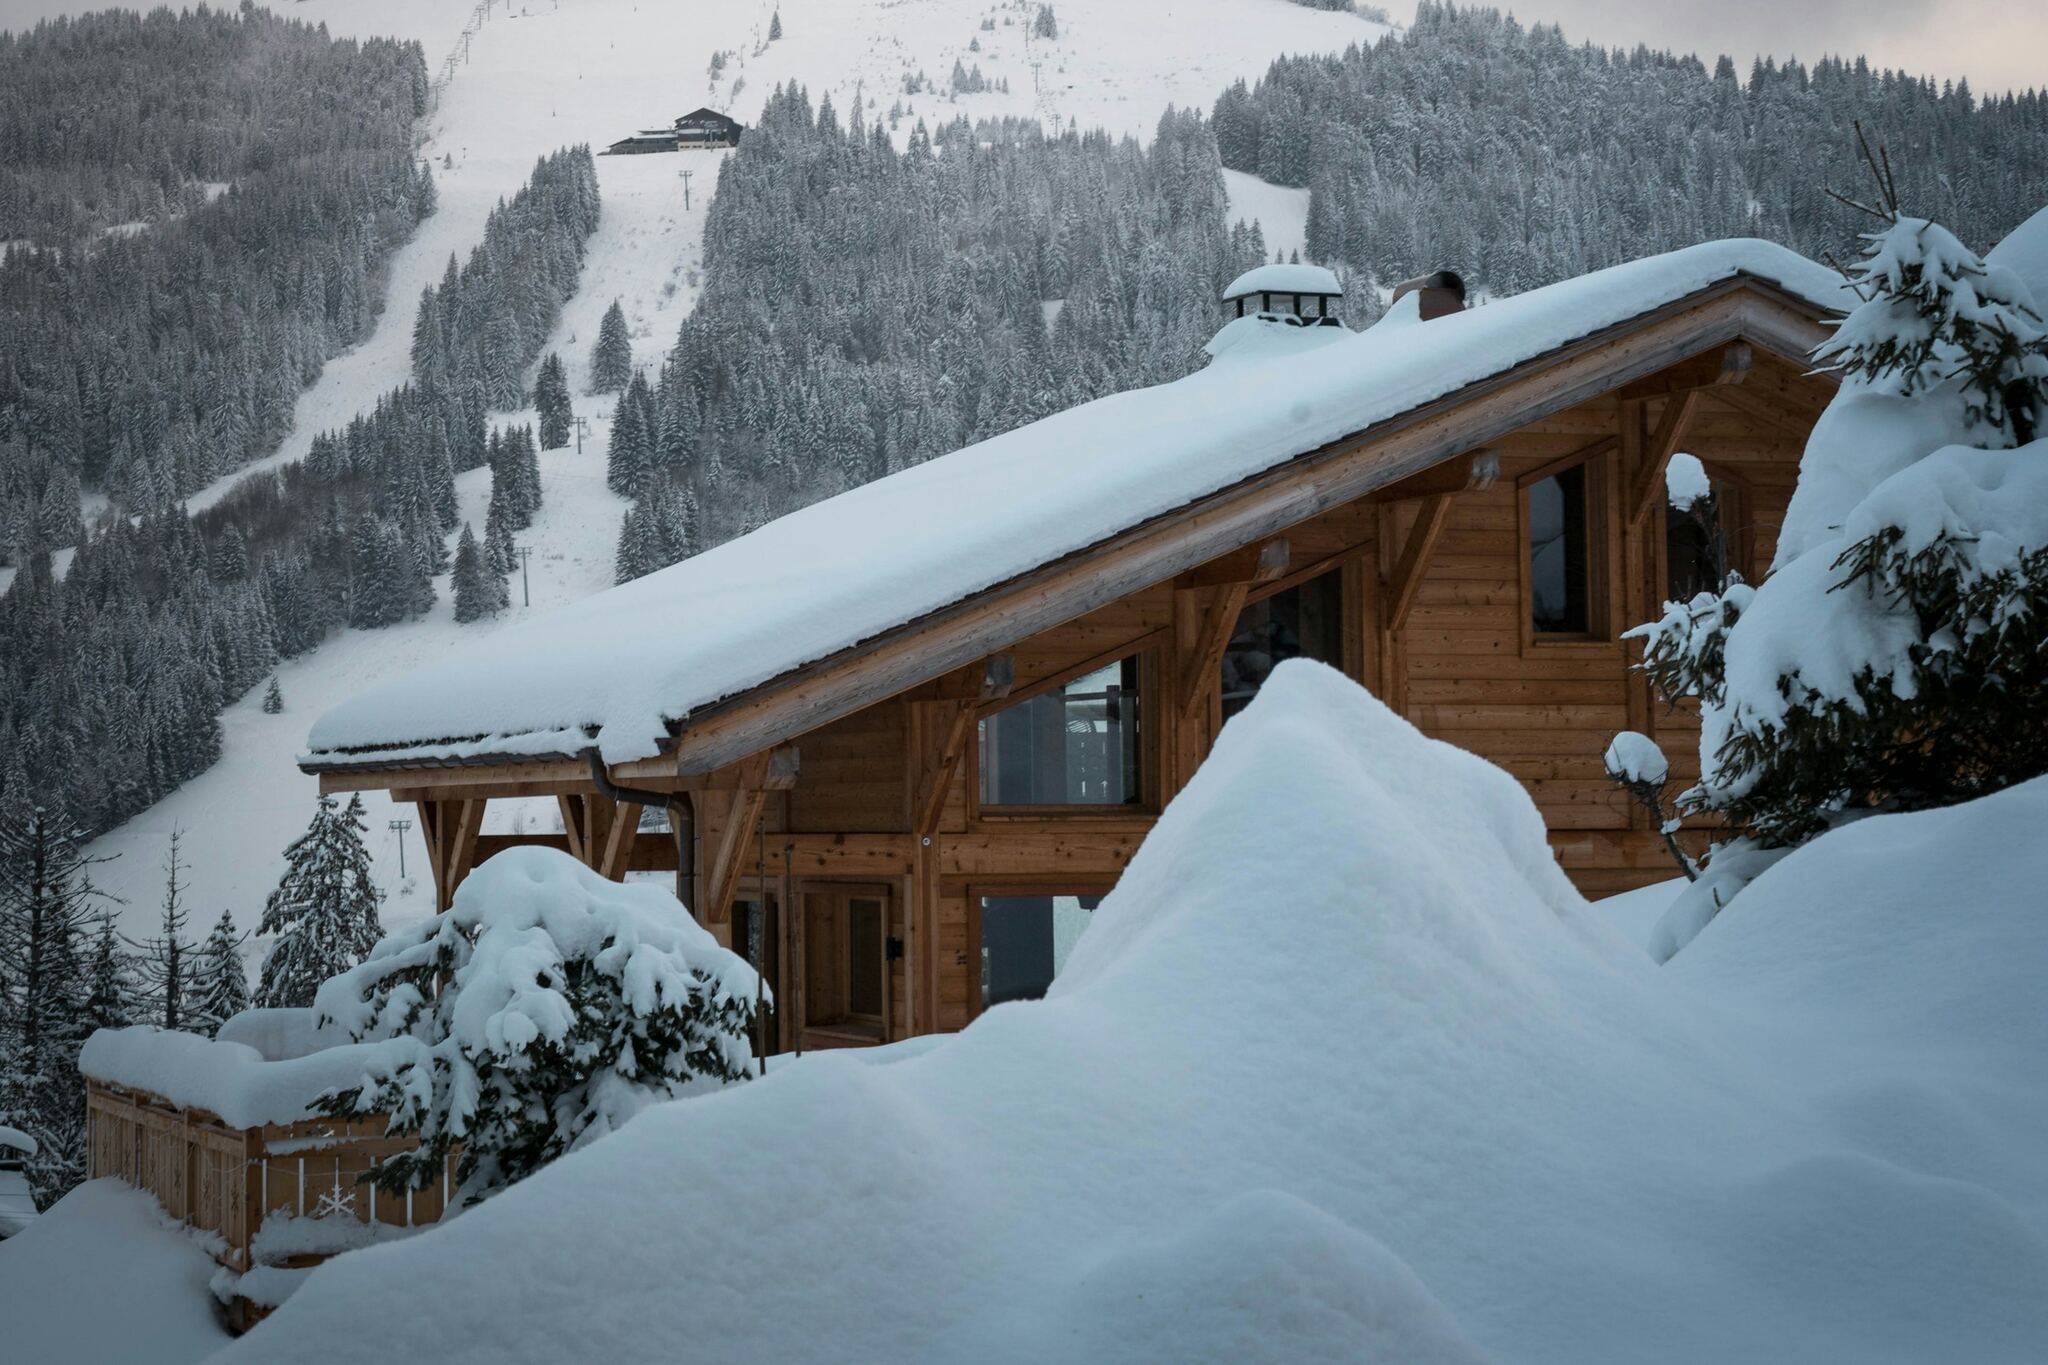 French AlpsHaute-Savoie charges the 5% rate while Hautes-Alpes stayed at 4.50%.
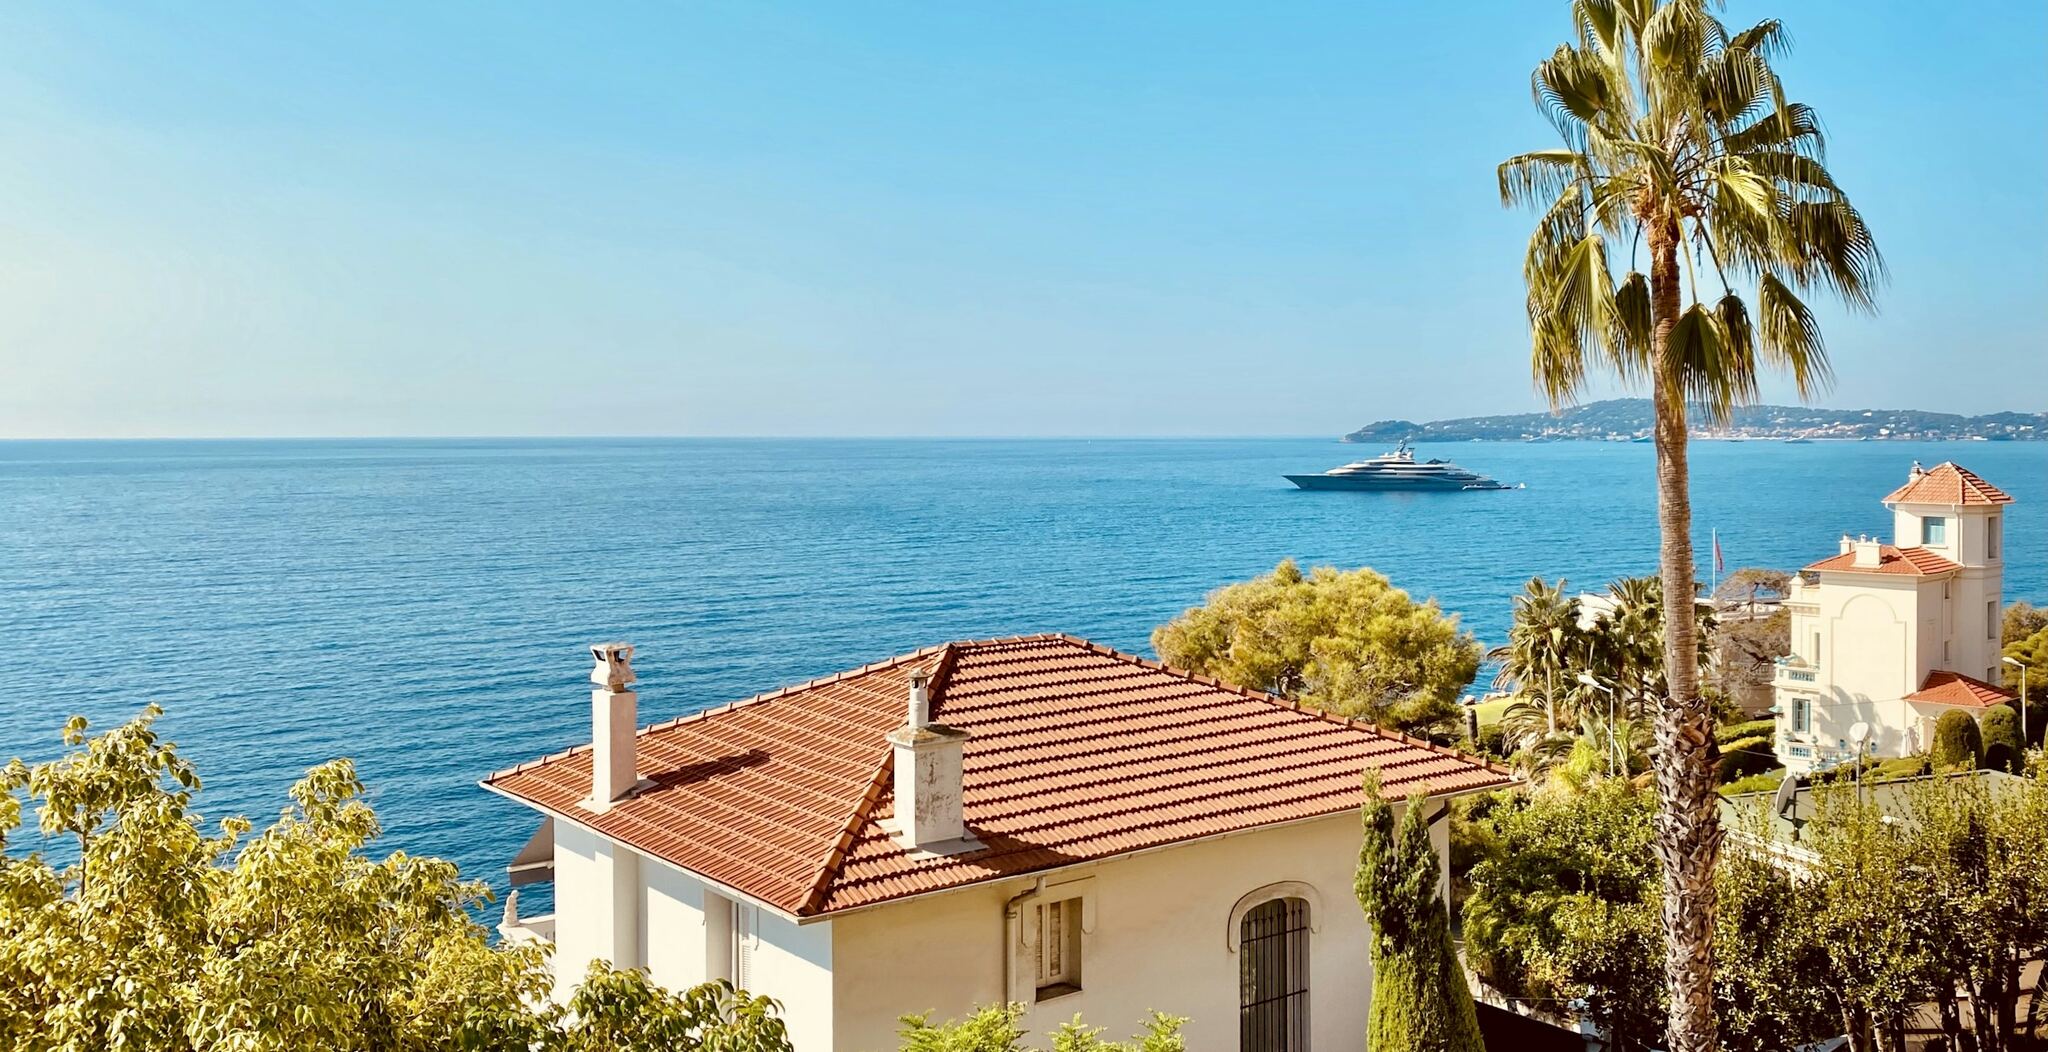 Côte d’AzurAlpes-Maritimes kept the 4.50% rate while neighbouring Var moved to 5%.
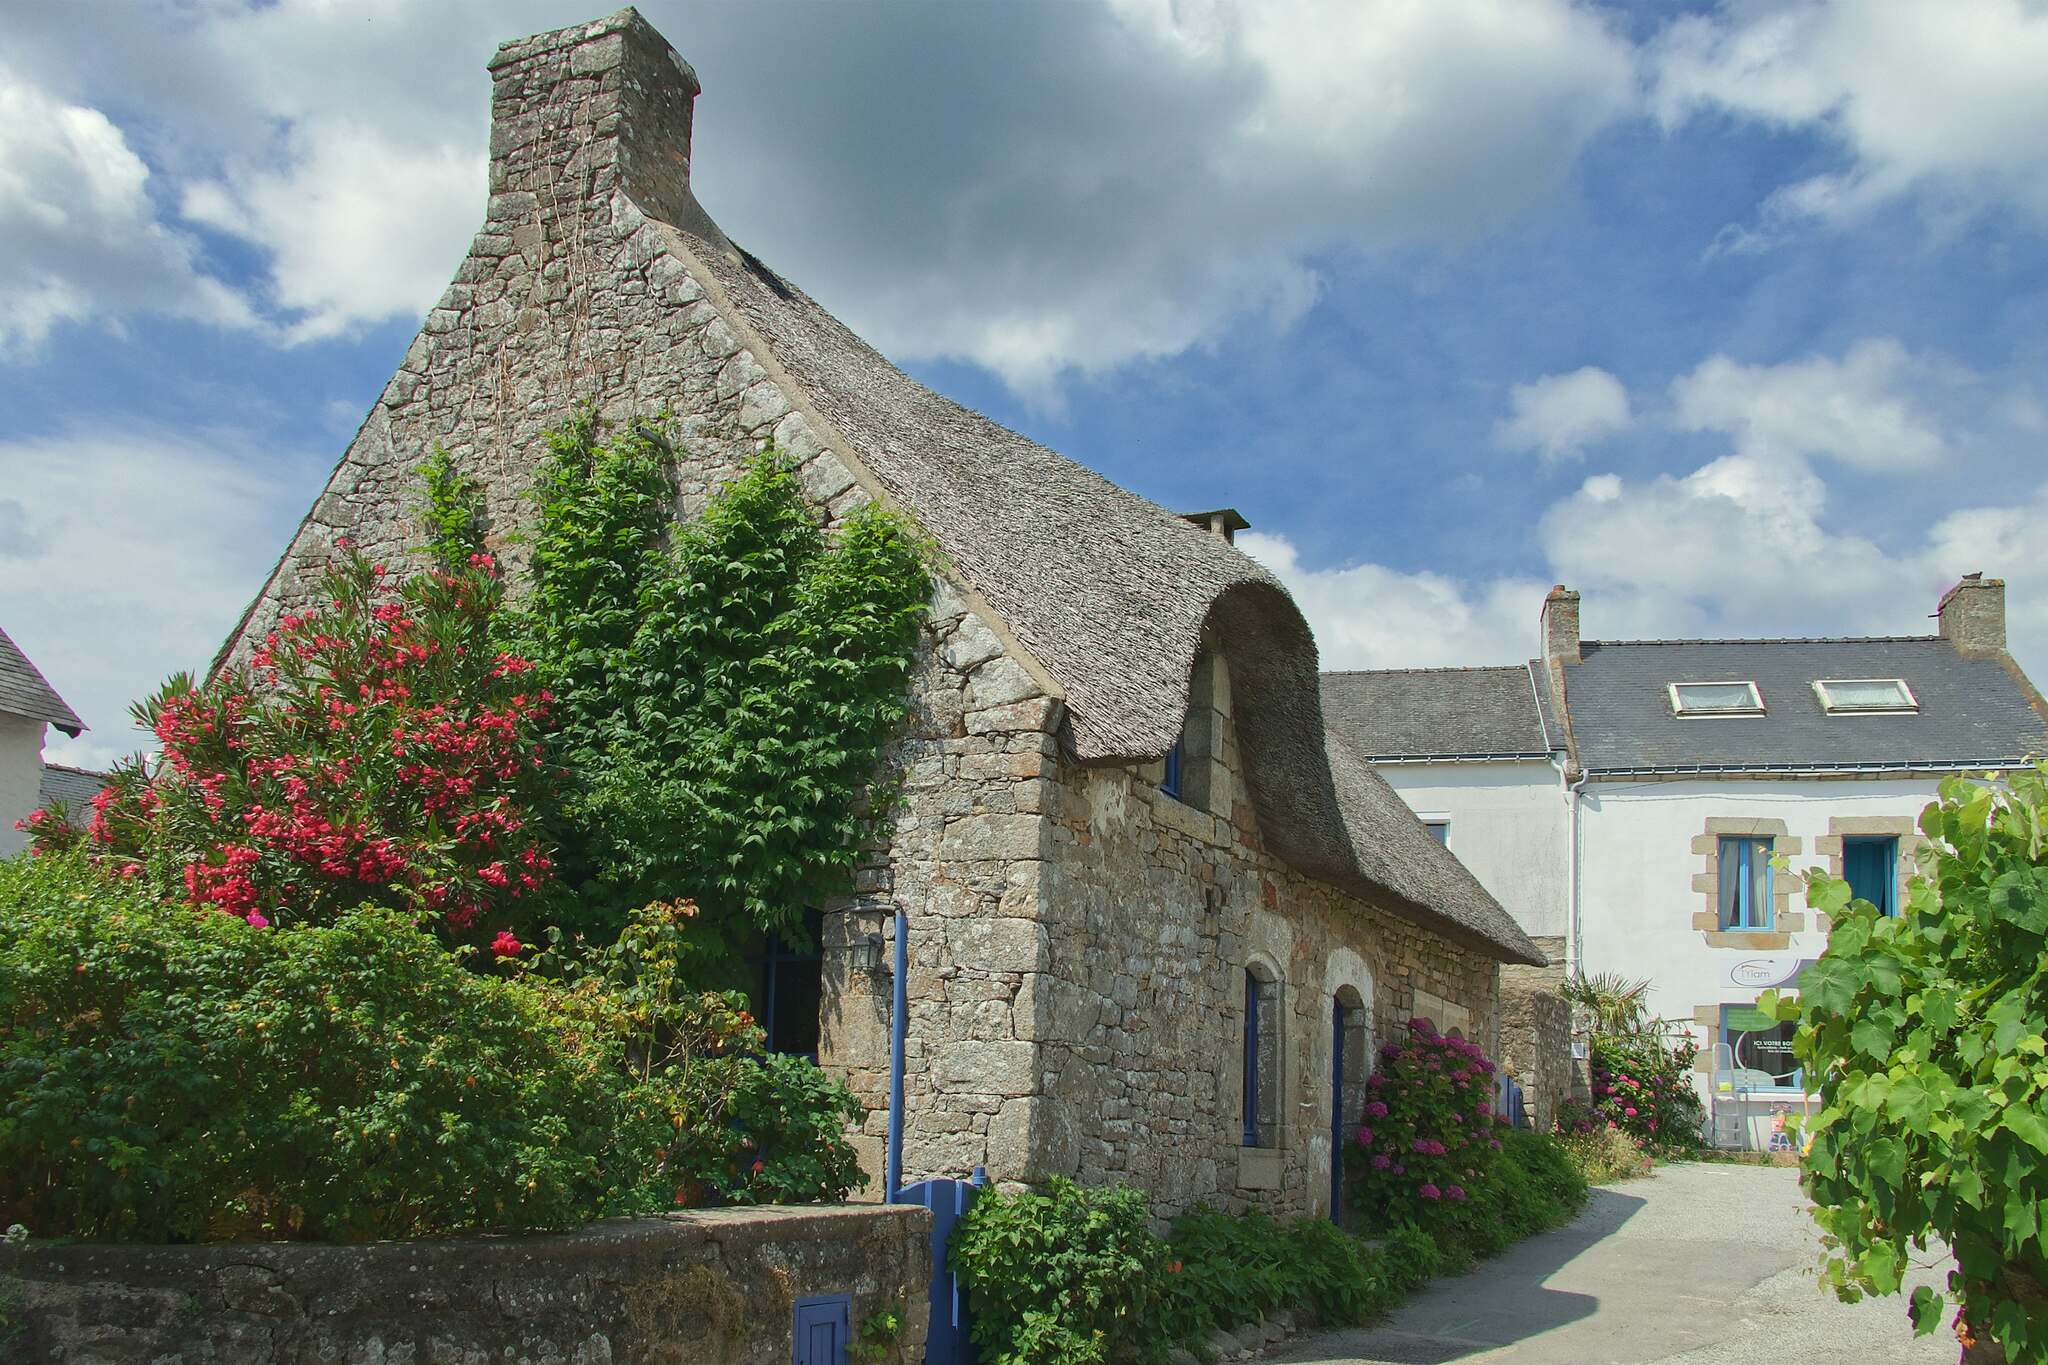 BrittanyAll four Brittany departments charge the 5% rate. Older houses rated E, F or G need an energy audit before sale.
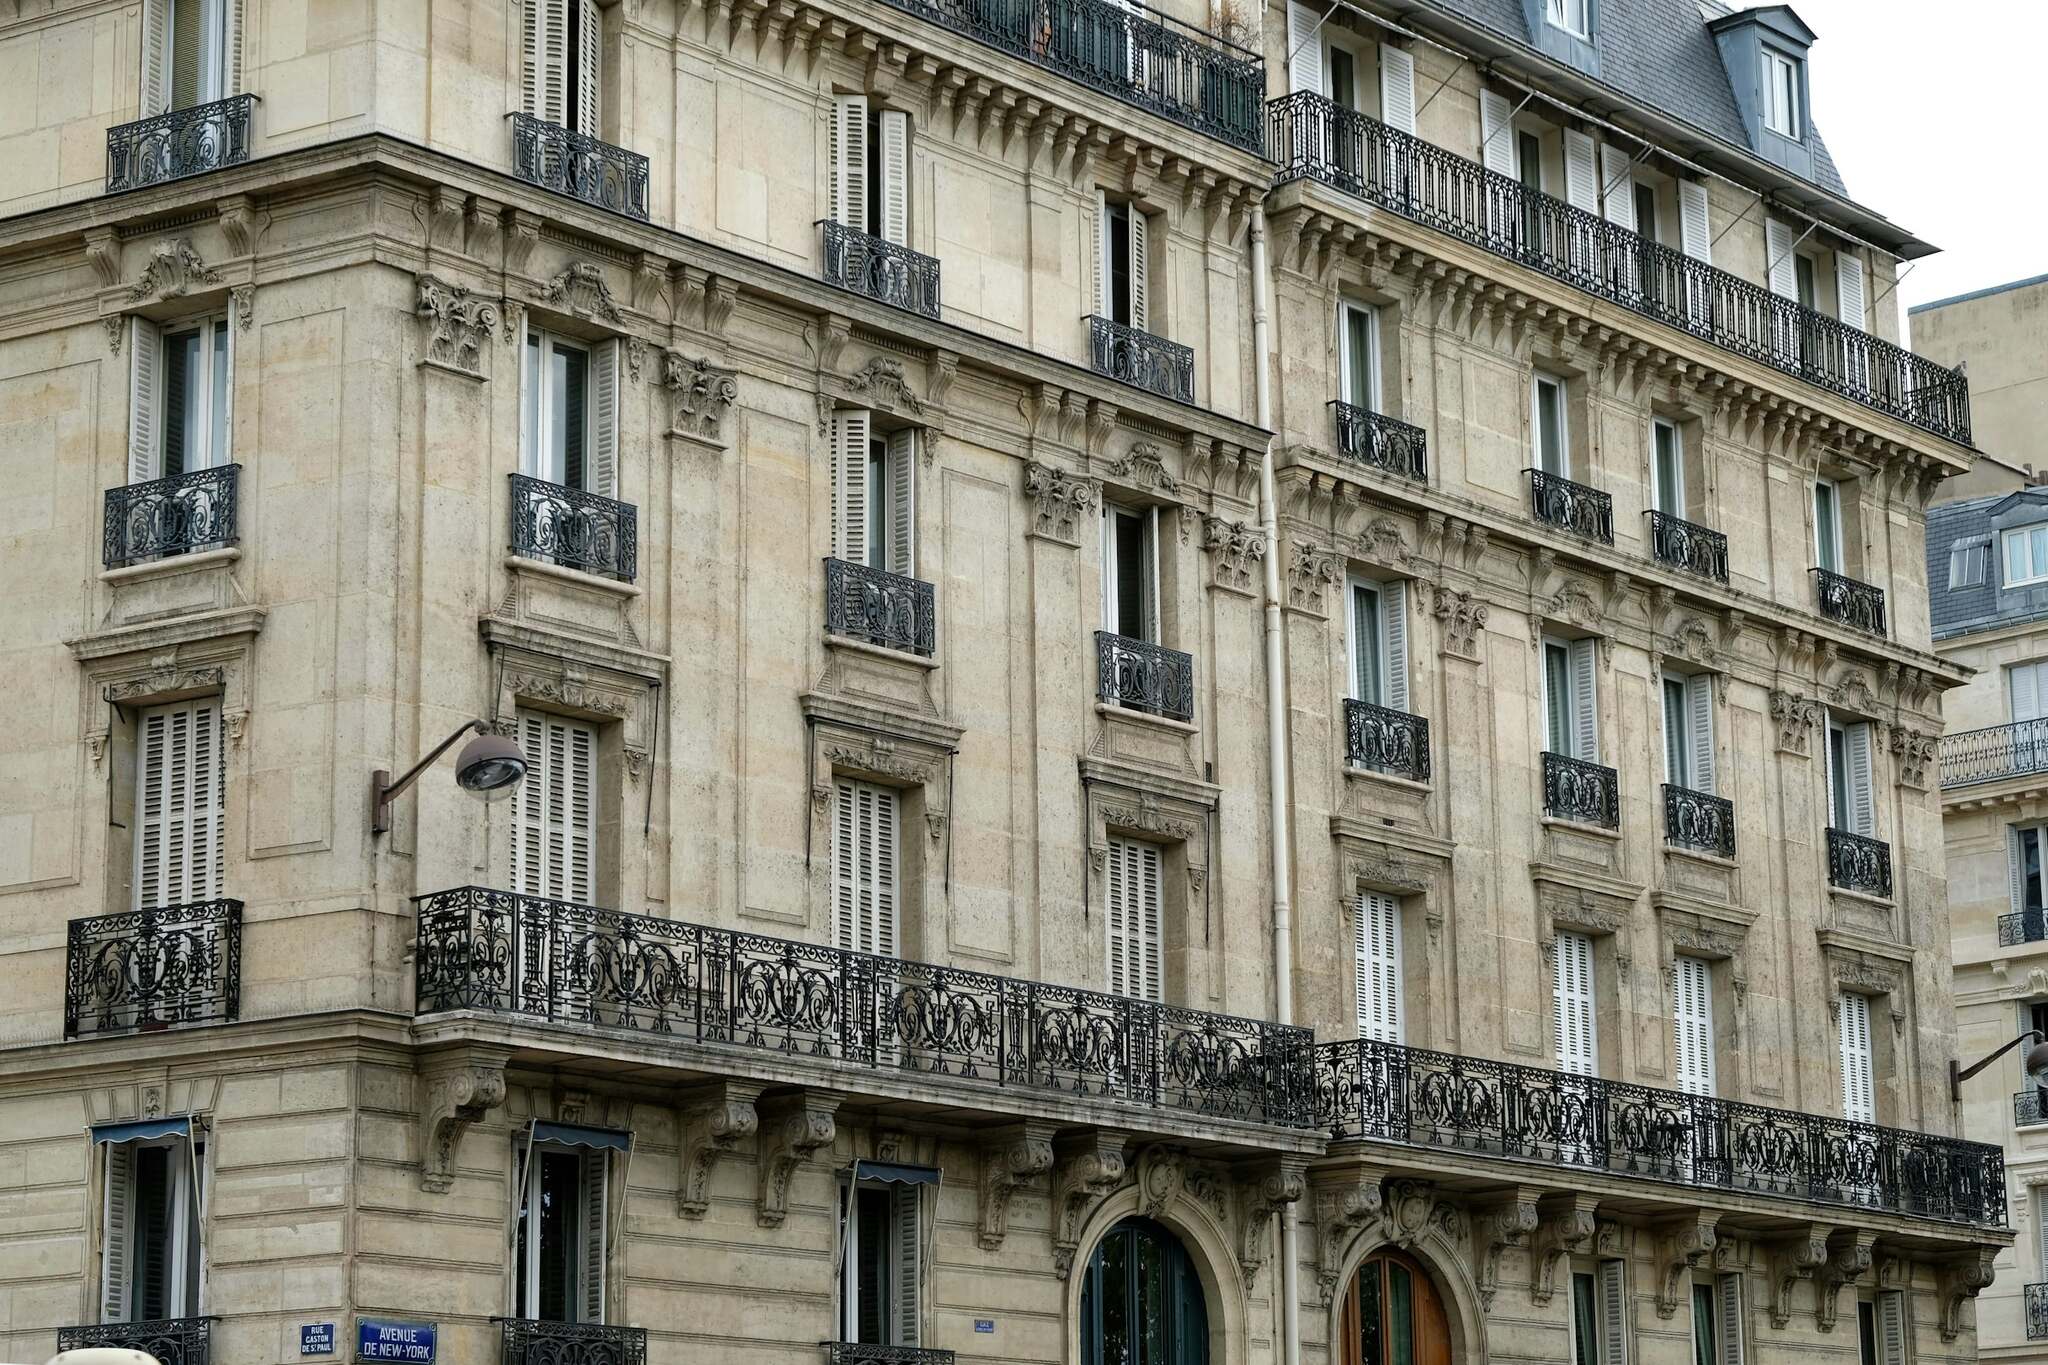 ParisParis charges the 5% rate. Most flats sit in a copropriété, so budget for the building’s service charges as well as the mortgage.
Departmental rates from the DGFiP table of 1 June 2026. Energy audit rule from Service-public.fr.
Guides UK and international buyers read first
Each guide answers one question properly, with French terms explained and figures dated. Start with the one that matches where you are.
- Can I get a French mortgage living outside France?Deposits, non-euro income, age limits and insurance.
- How buying in France works, step by stepFrom your offer to the notaire’s signing, with the timeline.
- What notaire fees really includePurchase tax, scale fees and disbursements, with worked examples.
- How much can I borrow?How the 35% rule, existing mortgages and rent are counted.
- Get a financing certificate before you offerWhy French agents ask for an attestation de financement.
Beyond the mortgage
Buying in France also means insuring the loan and the property, getting your money to the notaire in euros and, for many, moving house across a border. We can introduce you to the leading, reputable suppliers we work with for each, and they deal with you directly.
For estate agents in France
UK and international buyers on your books?
Let us prequalify your UK and international buyers so you only spend time on the ones who can complete. Refer a buyer who needs a mortgage and we introduce them to the specialists we work with, who work towards a firm loan offer in English. We keep you informed at each milestone the buyer agrees to share.
Agents immobiliers : nous préqualifions vos acquéreurs britanniques et internationaux pour que vous ne perdiez pas de temps, puis nous les accompagnons en anglais jusqu’à l’offre de prêt.
French Finance on WhatsApp
Rather talk it through on WhatsApp?
Ask your questions, send us a link to the property you like and take your enquiry forward on WhatsApp.
A person on our team replies in UK working hours. Message us any time and we will pick it up as soon as we are back.
Find out where you stand
Two short steps, no credit check. We read every enquiry, tell you honestly whether it is likely to be fundable and come back to you by email or phone.